


Composite Packaging Materials: Types, Benefits & Global Demand 2026
2026-06-19
1. Main Types of Composite Packaging Materials & Matching Application Scenarios (340–370 words)

Most low-ranking articles only list material names without market share ratios, structural composition and clear industry matching standards; this section supplements quantified market segmentation and practical selection logic based on 2026 industry data. 1.1 Four mainstream petroleum-based composite structures (80% global market share)
- Aluminum foil composite (37% market share): PET/AL/PE/EVOH ultra-high barrier laminates, blocks oxygen, moisture and UV light; core for coffee, pharmaceuticals and nutraceuticals with OTR ≤0.5cc/(㎡·24h)
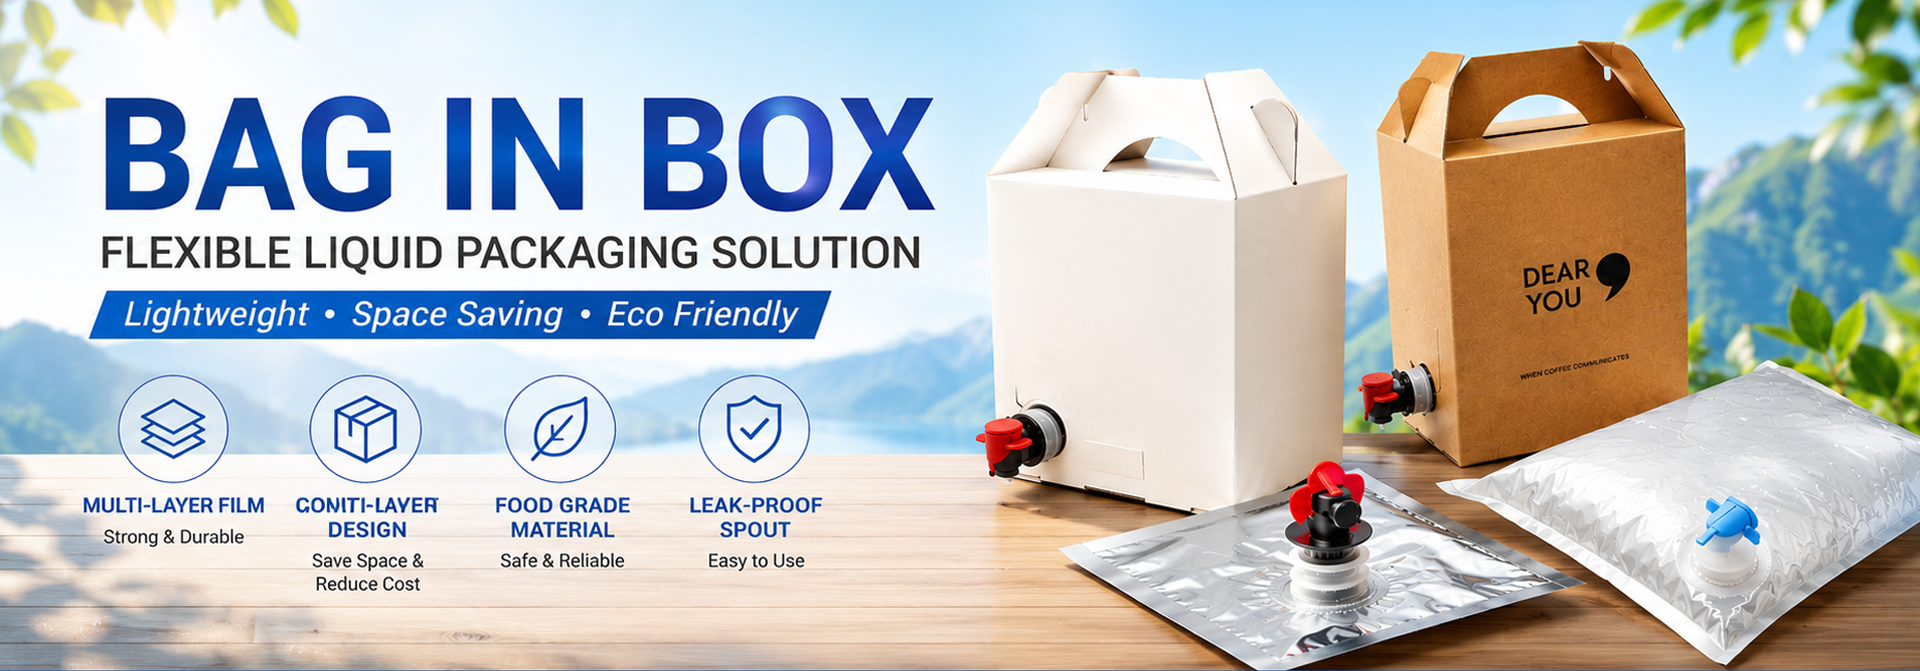
- Aluminum-plastic composite (28% share): Lightweight VMPET/PE low-cost barrier material, widely used for beverage pouches and daily cosmetics
- Nylon-reinforced PA composite: Excellent puncture resistance, suitable for frozen meat, granular chemicals and sharp hardware products
- Basic PET/PE plastic composite: Low-cost general-purpose material for dry snacks, e-commerce daily goods with basic moisture resistance 1.2 Fast-growing kraft paper-aluminum composite (21% share, highest growth rate) Kraft paper outer + aluminum barrier inner, balances eco appearance and preservation performance; favored by organic food and sustainable brands, meets EU PPWR low-plastic requirements 1.3 2026 emerging bio-based composite materials (14.2% annual CAGR) PLA/PBAT/starch biodegradable laminates and mono-material recyclable PE composite; solves multi-layer recycling pain points, compliant with global plastic restriction policies 1.4 Special functional customized composites Anti-static ESD composite for semiconductors, high-temperature retort composite for ready meals, UV-resistant composite for agricultural seeds
2. Core Quantifiable Benefits of Composite Packaging Materials vs Single-Layer Packaging (340–370 words)

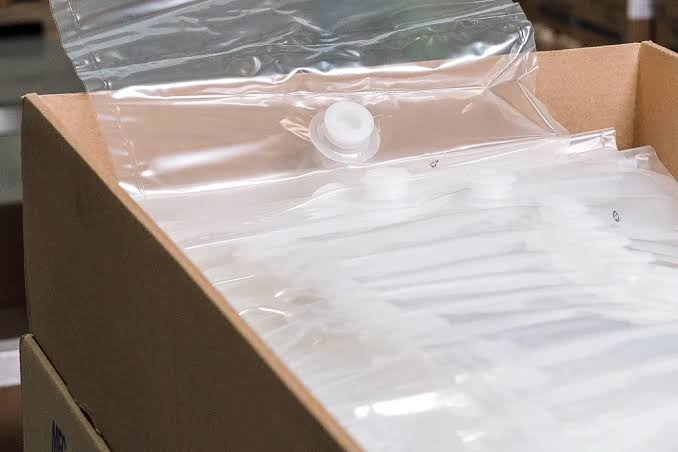
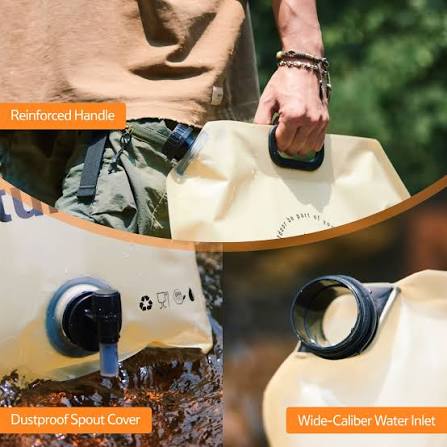
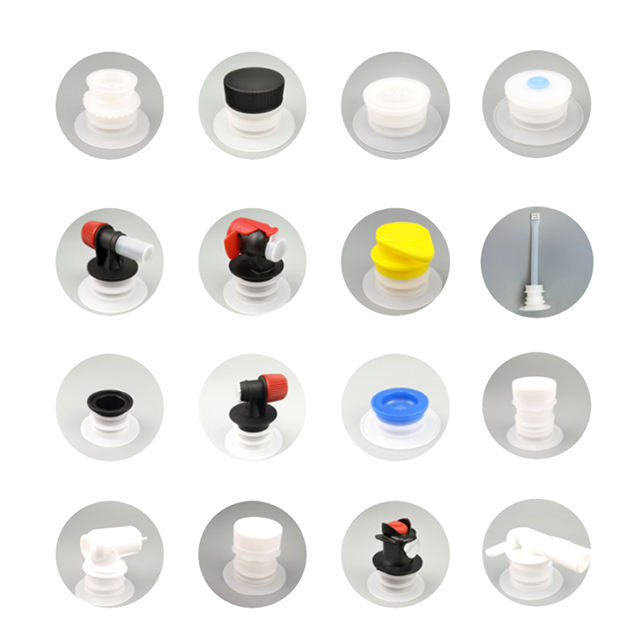
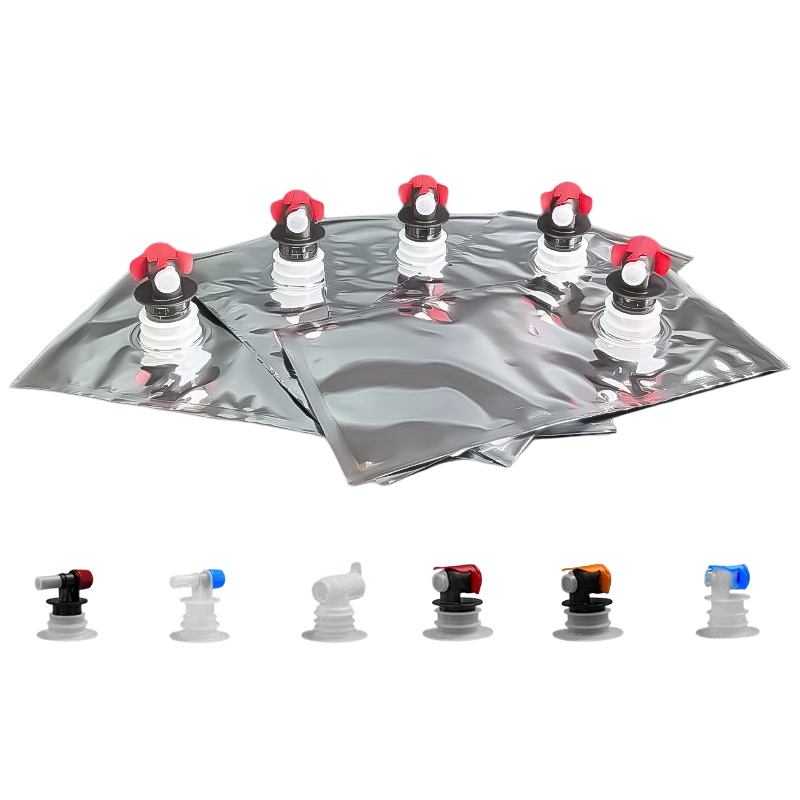
Competing content only describes vague advantages without measurable data contrast; this section uses test indicators and cost statistics to prove composite material comprehensive value. 2.1 Superior protective performance extends product shelf life greatly Multi-layer synergistic barrier reduces food spoilage rate by 46%; high tensile and puncture strength cuts transit damage by over 30% for cross-border logistics; temperature-adaptable structures cover -60°C cryogenic to 135°C retort scenarios 2.2 Logistics & storage cost optimization Composite bags are 20%–40% lighter than glass/metal rigid packaging, lowering ocean and air freight expenses; foldable flexible design saves 40% warehouse space and improves pallet loading efficiency 2.3 Brand customization & marketing advantages Supports 10-color high-definition gravure printing, matte/gloss tactile finishes and special structural designs (stand-up pouches, Spout Bags); premium composite packaging drives 5%–15% consumer price premium acceptance 2.4 Sustainable & compliance advantages for global export 2026 new mono-material and bio-composite materials avoid greenwashing risks; customizable food-grade laminates pass FDA, EU 10/2011 and regional EPR recycling rules to eliminate customs detention fines up to 4% of annual revenue
3. 2026 Global Composite Packaging Demand Data, Regional Breakdown & Growth Drivers (220–250 words)

Generic ranking articles lack complete regional market size and industry demand segmentation; this module integrates 2026 latest market research data for clear business reference. 3.1 Overall 2026 market scale Global composite Packaging Material market size reaches USD 12.80 billion, 7.2% CAGR from 2026 to 2033; food & beverage accounts for 42.1% of total consumption as the largest downstream industry 3.2 Regional demand distribution & characteristics
- Asia Pacific (38.5% share): Fastest growth, China as core production and consumption base, driven by domestic food processing and e-commerce boom
- North America (32.27% share): Prioritizes recyclable and smart composite packaging, strict FDA and Amazon packaging mandates
- Europe (20% share): Strict EU PPWR & EPR rules push mono-material eco composite demand
- Southeast Asia, Middle East & Latin America (9.23%): Rapidly rising demand for low-cost moisture-proof composite bags 3.3 Three core demand growth drivers in 2026
- Global plastic ban and carbon neutrality policies accelerate eco composite replacement
- E-commerce cross-border expansion boosts lightweight protective composite pouch consumption
- Pharmaceutical and organic food industry upgrade standards, raising demand for high-barrier certified composite materials
Conclusion (80–90 words)
Composite Packaging Materials cover multi-type layered structures with unmatched protective, cost and branding benefits. Supported by booming global cross-border demand in 2026, material selection must match product attributes, regional compliance rules and market consumption trends. Investing in proper composite structures helps brands reduce losses, avoid regulatory risks and capture market growth dividends.
FAQ
Q1: Which composite material is most suitable for EU export food products? A: Mono-material recyclable PE composite or kraft paper-aluminum eco laminates that meet EU PPWR recycled content standards. Q2: Why does aluminum foil composite occupy the largest market share? A: It provides all-round oxygen, moisture and light barrier performance, effectively extending shelf life for high-value sensitive products.