


Products News
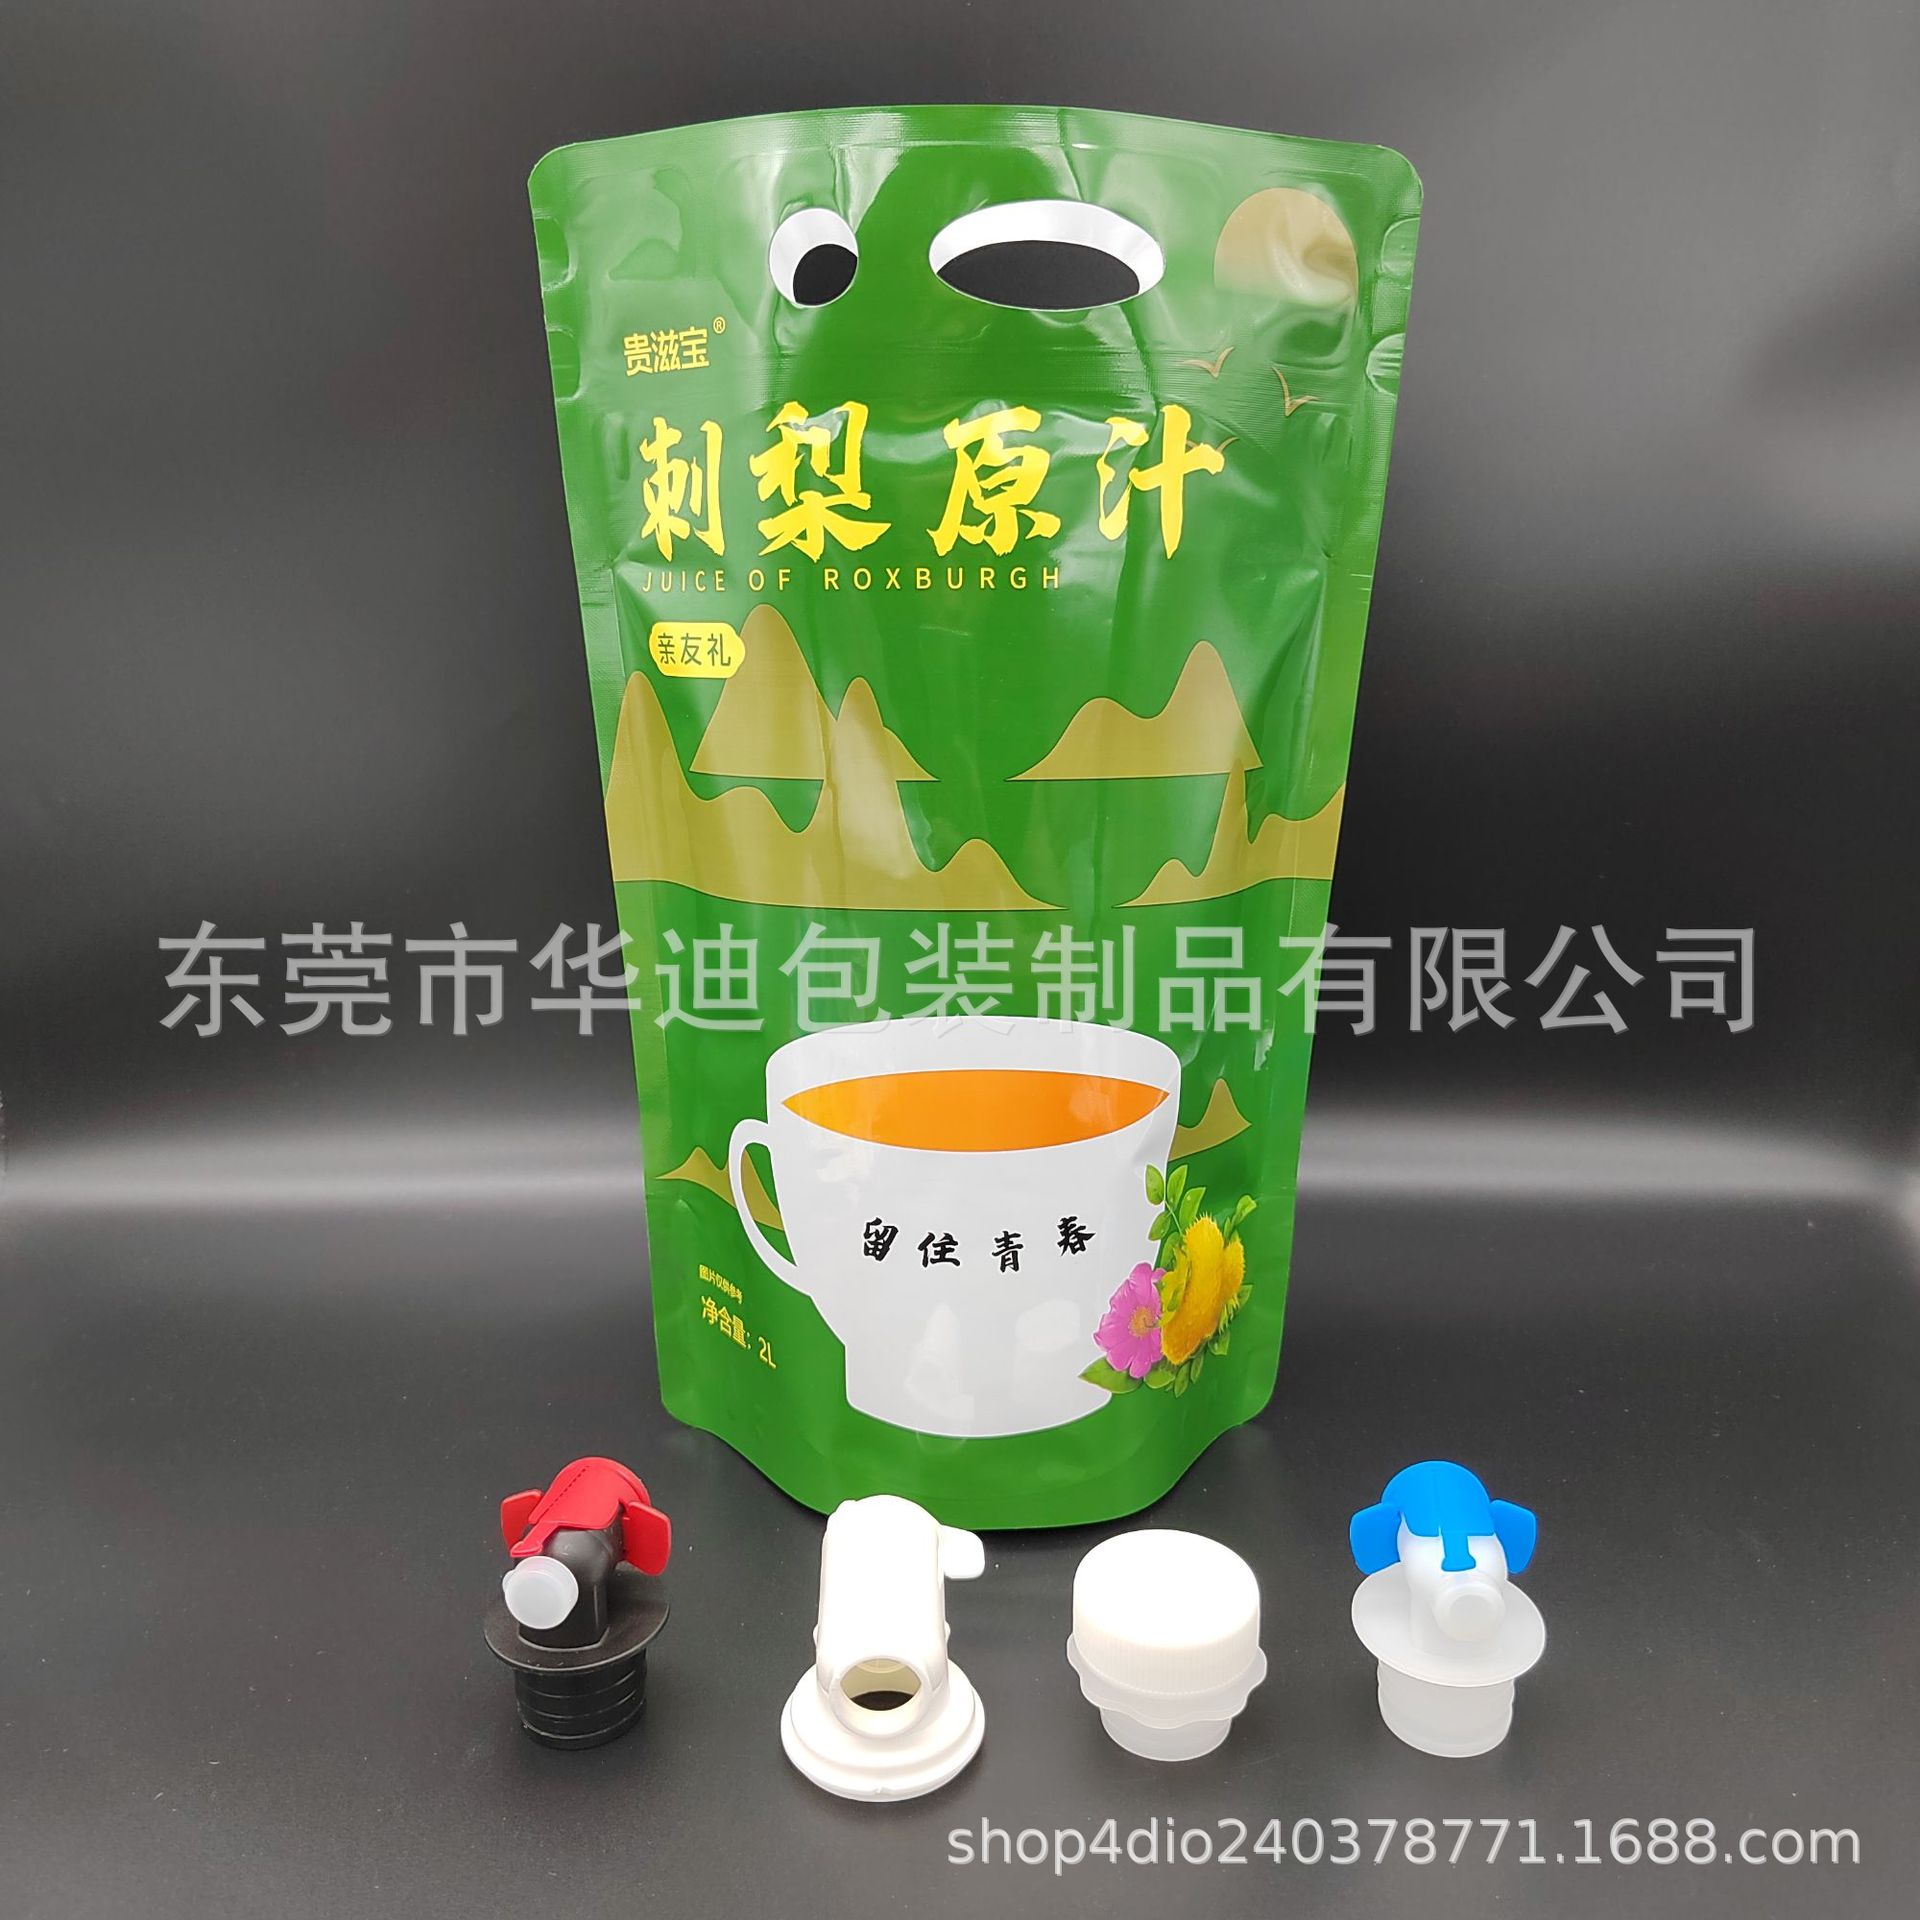
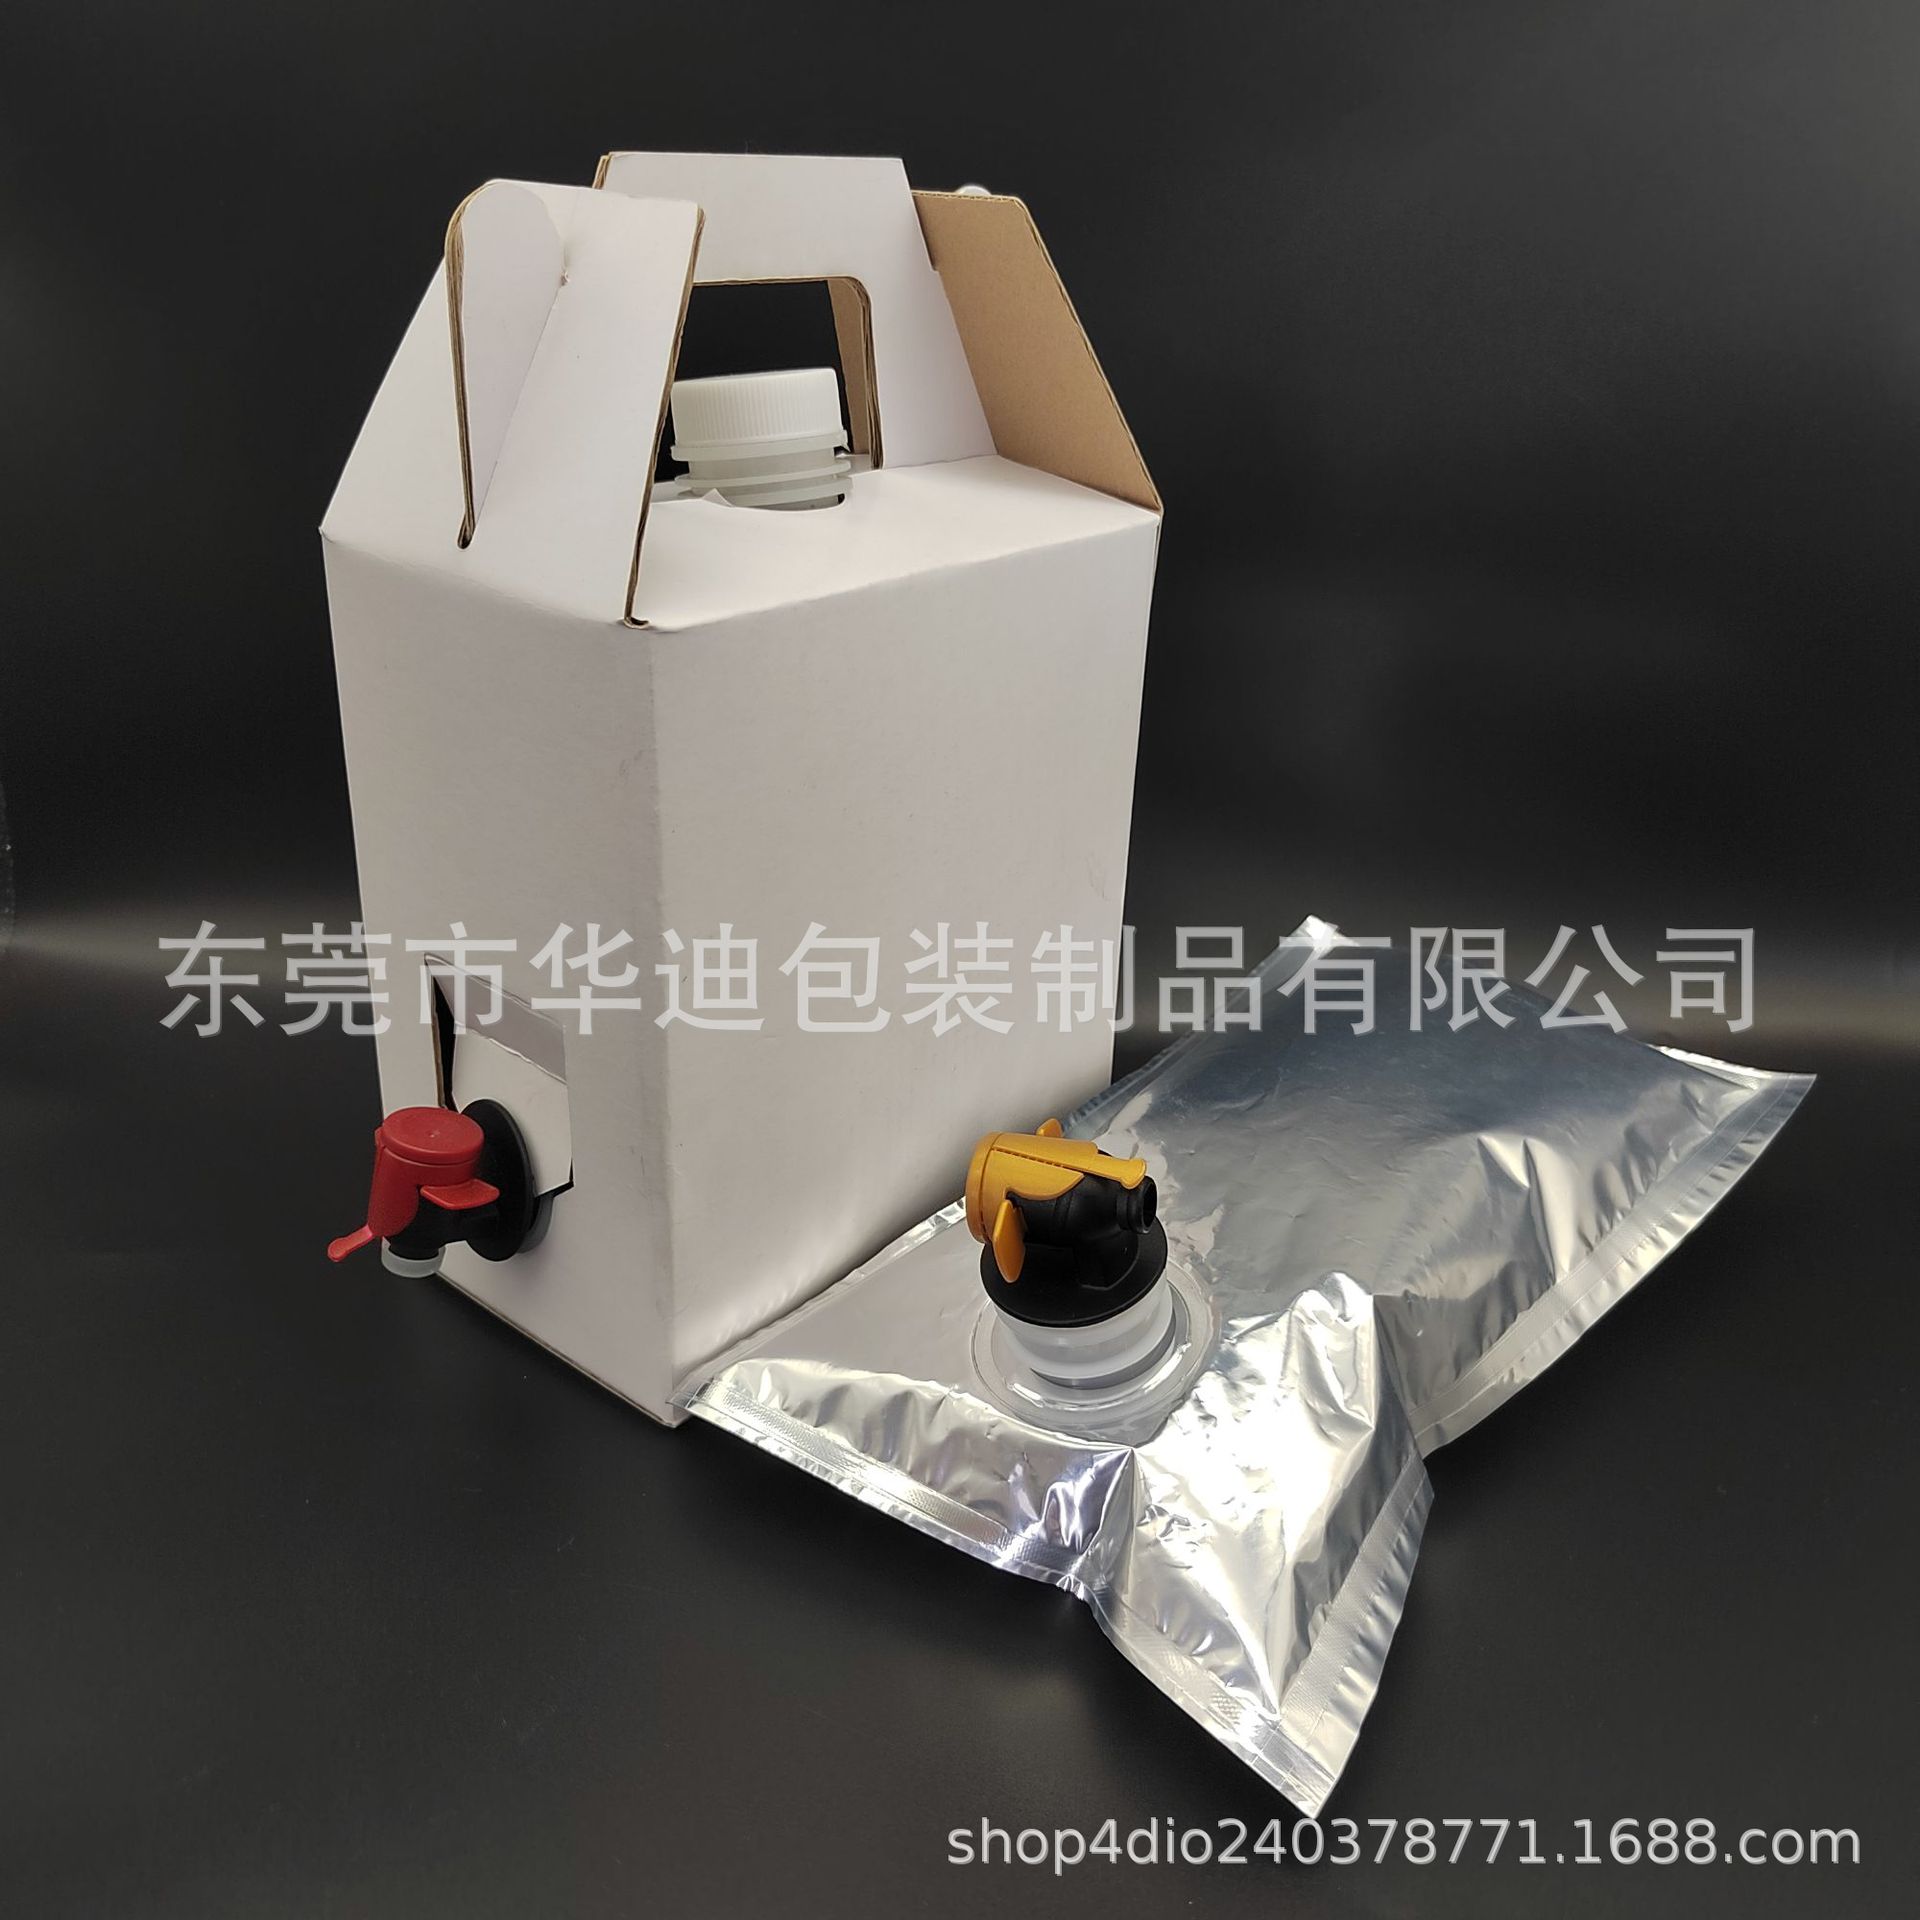
Composite Packaging Bags: Red Ocean vs Blue Ocean Market in 2026
2026-05-20
1. Composite Packaging Bags Red Ocean Market: Oversaturation & Price War Quagmire

Red ocean refers to low-value, standardized, oversupplied segmentsof composite Packaging Bags with brutal price competition and thin profit margins, where most suppliers fight for a shrinking share of existing demand.
1.1 Core Characteristics of Red Ocean
- Severe Overcapacity: 2026 China’s general composite bag capacity utilization is only 78%; over 60% of SMEs focus on low-entry products like 3-Side Seal and common stand-up bags.
- Fierce Price War: Homogeneous products (e.g., basic food and general merchandise bags) lead to 15–25% annual price cuts, with profit margins dropping to a meager 3–8%.
- Low Differentiation: 80% of small factories offer identical materials (PET/PE), printing, and sizes, lacking unique selling points to stand out.
- Concentration Pressure: Top 5 global players (Amcor, Sealed Air, etc.) hold 38.6% of the market share, leaving SMEs struggling to compete for survival.
1.2 Typical Red Ocean Segments
- Ordinary Food Composite Bags: Low-Barrier Packaging for snacks, dry goods, and common food—accounting for 60% of the market with an average margin of just 5%.
- General E-commerce Logistics Bags: Standard courier and express packaging that is oversupplied and purely price-driven, with no room for value addition.
- Low-End Industrial Bags: Simple-structured bags for chemicals and fertilizers, with prices undercut by Southeast Asian suppliers (Vietnam’s average wage is 57% of China’s).
1.3 Key Pain Points in Red Ocean
- Raw material price volatility (e.g., PE/PET fluctuations) squeezes already thin profits further.
- Rising labor and energy costs increase production expenses without room to raise prices.
- Environmental compliance (VOCs treatment, waste disposal) adds 8–12% to production costs, pressuring cash flow for small suppliers.
- Orders continue to shift to low-cost regions (Vietnam, Indonesia), reducing market share for high-cost manufacturers.
2. Composite Packaging Bags Blue Ocean Market: High-Value Niches & Low-Competition Growth
Blue ocean refers to high-value, technology-driven, underserved segmentsof composite Packaging Bags with low competition, high profit margins (20–40%), and strong growth potential, where suppliers create new demand instead of fighting over existing market share.
2.1 Core Characteristics of Blue Ocean
- High Technical Barriers: Requires expertise in high-barrier, sterile, heat-resistant, or sustainable materials and production processes.
- Strong Demand Growth: CAGR of 10–18% (vs. 3–5% in the red ocean), driven by consumption upgrades and strict regulatory requirements.
- Low Competition: Few qualified suppliers meet the technical and certification standards; CR5 (top 5 players) accounts for less than 25% in most blue ocean niches.
- High Margins: Profit margins of 25–40% (vs. 3–8% in the red ocean), with buyers less price-sensitive due to high value and compliance needs.
2.2 Top Blue Ocean Segments (2025–2026)
- Food-Grade High-Barrier Composite Bags: Retort pouches, Aseptic Packaging, and long-shelf-life food bags (ready meals, pet food) that meet FDA and EU safety standards.
- Medical & Pharmaceutical Composite Bags: Sterile, moisture-proof, and dust-proof packaging for drugs and medical devices, requiring strict ISO 13485 certification and low competition.
- Sustainable & Recyclable Composite Bags: Mono-material, biodegradable, and compostable structures, driven by EU PPWR and China’s “dual carbon” policies with a CAGR of 15.2%.
- Smart & Functional Composite Bags: Temperature-indicating, anti-counterfeit, oxygen-absorbing, and zipper/spout-equipped bags with high added value.
- New Energy & Electronic Packaging: Anti-static, moisture-proof bags for batteries and semiconductors, with an 18% growth rate as tech companies expand into the space.
- Premium Cosmetics & Personal Care Bags: Luxury printing, special textures, and high-end branding, with profit margins of 35–40%.
2.3 Key Drivers of Blue Ocean Growth
- Regulatory Push: EU PPWR (Packaging and Packaging Waste Regulation) and China’s “dual carbon” goals force brands to adopt sustainable packaging solutions.
- Consumption Upgrade: Global consumers demand safer, more convenient, and eco-friendly packaging for food, cosmetics, and medical products.
- Tech Innovation: Solvent-free lamination, digital printing, and mono-material barrier technologies reduce production costs and improve product performance.
- Niche Market Expansion: Rapid growth in pet food, plant-based food, and medical sectors creates new demand for specialized composite packaging.
3. Red Ocean vs Blue Ocean: Direct Comparison (2026 Data)

Understanding the key differences between red and blue ocean markets for composite packaging bags is critical for suppliers and buyers to make strategic decisions, with clear gaps in product value, competition, and growth potential:
- Product Type: Red ocean markets focus on standard, low-value composite bags (common food, logistics packaging), while blue ocean markets specialize in high-barrier, sustainable, smart, medical, and new energy-related packaging.
- Profit Margin: Red ocean margins are only 3–8% due to price wars, whereas blue ocean margins range from 20–40% thanks to high value and low competition.
- Competition Intensity: Red ocean markets are extremely fierce, with suppliers competing primarily on price; blue ocean markets have low competition, with barriers to entry rooted in technology and certifications.
- Capacity Utilization: Red ocean capacity utilization is 70–80% (oversupplied, with idle production lines), while blue ocean capacity utilization is 90–98% (tight supply, with high demand for qualified products).
- Growth Rate: Red ocean markets grow at a stagnant 3–5% annually, while blue ocean markets expand at 10–18% due to rising demand for high-value products.
- Entry Barriers: Red ocean entry barriers are low (basic production equipment and minimal certifications), while blue ocean barriers are high (significant R&D investment, technical expertise, and strict international certifications).
- Key Risks: Red ocean risks include price collapse, order loss, and unsustainable low profits; blue ocean risks center on high R&D costs, compliance challenges, and rapid technical iteration.
4. How to Shift from Red Ocean to Blue Ocean: Winning Strategies
For composite packaging bag suppliers trapped in the red ocean, shifting to blue ocean niches is the only path to sustainable growth. Below are actionable strategies to break free from price competition:
4.1 Product Innovation: Upgrade to High-Value Niches
- Abandon standard, low-margin products and focus on high-barrier, retort, or mono-material recyclable composite bags that meet market demand for safety and sustainability.
- Add value-added functions: anti-counterfeit features, temperature control indicators, easy-tear designs, or zipper/spout accessories to differentiate products.
4.2 Technical Upgrading: Build Core Barriers
- Adopt eco-friendly and cost-effective production technologies, such as solvent-free lamination and digital printing, to reduce costs and meet environmental regulations.
- Invest in R&D for sustainable materials (biodegradable PLA/PBAT, mono-material PE) to align with global eco-trends.
- Obtain key international certifications: FDA, EU food safety standards, ISO 13485 (medical), and eco-labels to qualify for blue ocean segments.
4.3 Market Positioning: Target High-End Buyers
- Shift focus from price-sensitive SMEs to high-end buyers: international food brands, medical device companies, premium cosmetics firms, and new energy enterprises.
- Target high-growth regions: RCEP, Middle East, and Latin America, where blue ocean segments are less saturated than in the EU and US.
4.4 Cost & Brand Optimization
- Automate production lines to cut labor costs and improve efficiency (20–30% efficiency gain on average).
- Build a brand around quality, technical expertise, and sustainability—avoid competing solely on price, which is the red ocean’s biggest trap.
Conclusion
The composite packaging bag market is polarizing: red ocean segments face oversupply, brutal price wars, and minimal profits, while blue ocean niches offer low competition, high margins, and strong growth potential.
For suppliers, escaping the red ocean requires strategic product innovation, technical upgrading, and high-end market positioning. For buyers, partnering with blue ocean suppliers ensures better product quality, compliance, and long-term stability.
As sustainability and technology reshape the industry, the blue ocean for composite packaging bags will expand rapidly—making it the key to sustainable success in 2026 and beyond.